Economics : Break-Even
Showing 3 Results
RS
100
-
20
40
60
80
TMS
Stella
Kraken
Mariner
Western Isles
Barnett
Arkoma Woodford
Granite Wash
Fayetteville
Uinta Basin
Mississippi Lime
Libra
Big Foot
Utica
120Energy Group; /bbl WTI
Upper Devonian
Gulf Coast
Atlanta-Oliva
Piceance Basin
Jack/St Malo
Perdido
Shenandoah
Martin Linge
Ivar Aasen
Amoca
Anchor
Stampede
Cascade/Chinook
North Park Basin
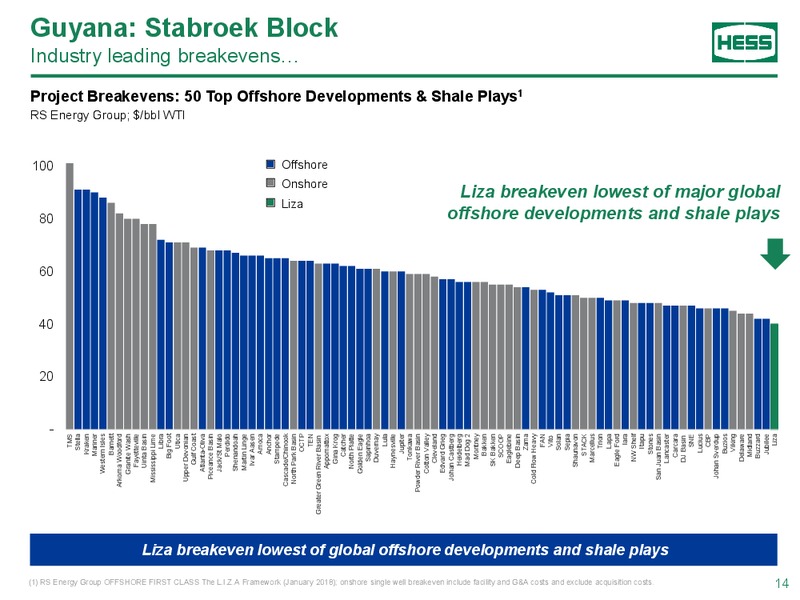
Industry leading breakevens
Liza
OCTP
TEN
Greater Green River Basin
Onshore
Offshore
Appomattox
Guyana: Stabroek Block
Gina Krog
Catcher
North Platte
Golden Eagle
Sapinhoa
Duvernay
Lula
Haynesville
Jupiter
Tonkawa
Powder River Basin
Cotton Valley
Cleveland
Edvard Grieg
Johan Castberg
Heidelberg
Mad Dog 2
Montney
Bakken
SK Bakken
SCOOP
Eaglebine
Deep Basin
Project Breakevens: 50 Top Offshore Developments & Shale Plays1
Zama
Cold Flow Heavy
FAN
Vito
Solan
Sepia
Shaunavon
STACK
Marcellus
Trion
Lapa
Eagle Ford
Iara
NW Shelf
Itapu
(1) RS Energy Group OFFSHORE FIRST CLASS The L.I.Z.A Framework (January 2018); onshore single well breakeven include facility and G&A costs and exclude acquisition costs.
Stones
San Juan Basin
Liza breakeven lowest of global offshore developments and shale plays
Lancaster
Carcara
DJ Basin
SNE
Lucius
CBP
Johan Sverdup
Buzios
Viking
Delaware
Midland
Buzzard
Jubilee
Liza
offshore developments and shale plays
Liza breakeven lowest of major global
14
Hess Corp
February 2019

Focus Assets Btax Breakeven 10% (1)
1) Breakeven analysis discounted at 10 percent before tax, based on internal type well assumptions using constant costs, FX rate of 0.80 US/C and AECO basis of US1.00/MMbtu. Breakeven oil
prices based on a constant NYMEX gas price of US3.00/MMbtu. Breakeven gas prices based on a constant WTI oil price of US50.00/Bbl. Refer to the heading Reserves and Other Information in
the Advisories Appendix.
28
Paramount Resources Ltd.
September 2018

Growing Onshore Production While Increasing Low Break-Even Locations
Net Production, MBOEPD
100 1,800
Eagle Ford Shale 90 1,600
1,000 Economic Locations* Below 40 WTI 80 1,400
Production, MBOEPD
70
1,200
CAPEX, MM
More than 500 Remaining Catarina Locations 60
1,000
50
800
5.3 MM Well Cost 40
600
30
20 400
Kaybob Duvernay 10 200
255 Economic Locations* Below 40 WTI at 0
2012
2015 2013
2016 2014
2017 2018 2019 2020 2021 2022
0
Current Well Cost Eagle Ford Shale Kaybob/Placid CAPEX
Multi-Year Plan Assumes WTI 52/BBL & HH 3.00/MCF, Escalated at 5%
Targeting Drilling & Completion Cost 6.5 MM 140
Eagle Ford Shale vs Kaybob Duvernay 2017 Well Performance
1,150 Economic Locations* Below 40 WTI at 120
Cumulative Production, MBOE
Targeted Well Cost 100
80
60
40
20
0
0 10 20 30
30 40
40 50
50 60
60 70
70 80
80 90
90 100
100
DaysononProduction
Days Production
*Economic Location Generates 10% IRR Karnes 2017 Avg Karnes 2017 Catarina
Avg Catarina
2016-2017 Avg 2016-2017 Duvernay
Avg 2017 Wells
MURPHY OIL CORPORATION www.m urp h yo i lc o rp.c om NYSE: MUR 34
Murphy Oil Corp
May 2018