Economics : Break-Even
Showing 3 Results

2016-2019 Transformation Recap
FINANCIAL OPERATIONS PORTFOLIO STRATEGY
Capital discipline; Optimized model Completed 19B Robust strategic
significant free cash for development of asset sales planning for long-term
flow generation of unconventionals value creation
Completed high-value
Reduced debt from Achieved project acquisitions in Alaska, Returned 44% of
27B to 15B startups in Alaska, Canada and Lower 48 CFO3 to shareholders
Norway and China
Single A- rated Increased resource base of
balance sheet Strong safety
<40/BBL WTI cost of supply
Progressed performance and continued
from 10 BBOE to 15 BBOE
Ending cash1 of 8.4B exploration/appraisal ESG leadership
in Alaska and Montney
Lowered breakeven
Total liquidity2 of 14B price for our business
ACTIONS TAKEN OVER 3 YEARS PUT OUR COMPANY IN A COMPETITIVELY ADVANTAGED POSITION
1Ending cash includes cash, cash equivalents and restricted cash totaling 5.4B and short-term investments of 3.0B. Restricted cash was 0.3B. 2 Liquidity is defined on our website under Other Terms.
3 2017-2019 cash provided by operating activities was 31.1B. Excluding operating working capital change of (0.6B), cash from operations was 31.7B. Cash from operations (CFO) is a non-GAAP measure further defined on our website.
3
ConocoPhillips
May 2020
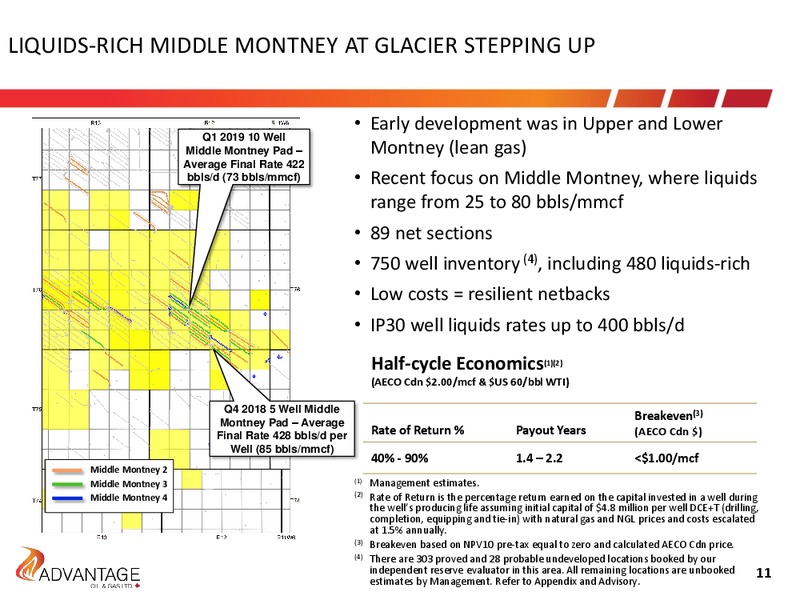
LIQUIDS-RICH MIDDLE MONTNEY AT GLACIER STEPPING UP
Early development was in Upper and Lower
Q1 2019 10 Well
Middle Montney Pad Montney (lean gas)
Average Final Rate 422
bbls/d (73 bbls/mmcf) Recent focus on Middle Montney, where liquids
range from 25 to 80 bbls/mmcf
89 net sections
750 well inventory (4), including 480 liquids-rich
Low costs = resilient netbacks
IP30 well liquids rates up to 400 bbls/d
Half-cycle Economics(1)(2)
(AECO Cdn 2.00/mcf & US 60/bbl WTI)
Q4 2018 5 Well Middle
Montney Pad Average
Breakeven(3)
Final Rate 428 bbls/d per Rate of Return % Payout Years (AECO Cdn )
Well (85 bbls/mmcf)
40% - 90% 1.4 2.2 <1.00/mcf
Middle Montney 2
Middle Montney 3 (1) Management estimates.
(2) Rate of Return is the percentage return earned on the capital invested in a well during
Middle Montney 4
the wells producing life assuming initial capital of 4.8 million per well DCE+T (drilling,
completion, equipping and tie-in) with natural gas and NGL prices and costs escalated
at 1.5% annually.
(3) Breakeven based on NPV10 pre-tax equal to zero and calculated AECO Cdn price.
(4) There are 303 proved and 28 probable undeveloped locations booked by our
independent reserve evaluator in this area. All remaining locations are unbooked 11
estimates by Management. Refer to Appendix and Advisory.
Advantage Energy Ltd.
December 2019
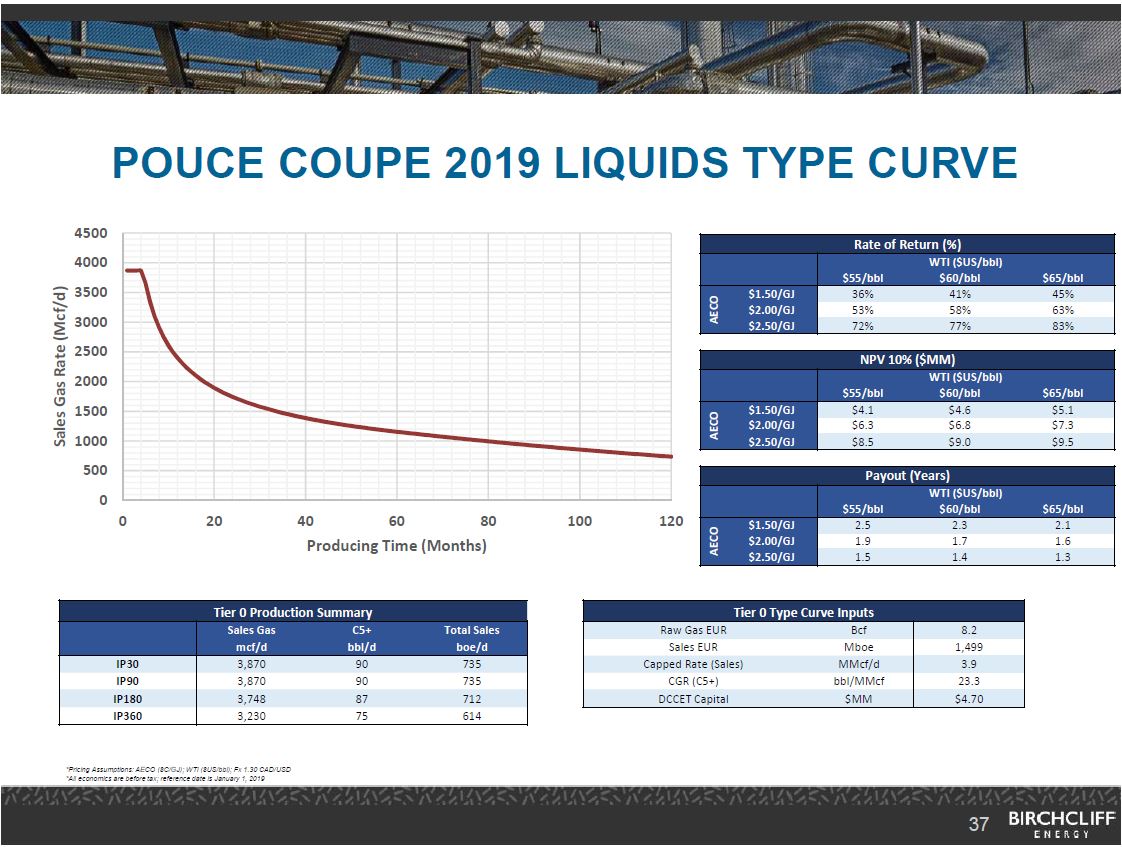
POUCE COUPE 2019 LIQUIDS TYPE CURVE
0
500
1000
1500
2000
2500
3000
3500
4000
4500
0 20 40 60 80 100 120
Sales Gas Rate (Mcf/d)
Producing Time (Months)
Rate of Return (%)
WTI ($US/bbl)
$55/bbl $60/bbl $65/bbl
AECO
$1.50/GJ 36% 41% 45%
$2.00/GJ 53% 58% 63%
$2.50/GJ 72% 77% 83%
NPV 10% ($MM)
WTI ($US/bbl)
$55/bbl $60/bbl $65/bbl
AECO
$1.50/GJ $4.1 $4.6 $5.1
$2.00/GJ $6.3 $6.8 $7.3
$2.50/GJ $8.5 $9.0 $9.5
Payout (Years)
WTI ($US/bbl)
$55/bbl $60/bbl $65/bbl
AECO
$1.50/GJ 2.5 2.3 2.1
$2.00/GJ 1.9 1.7 1.6
$2.50/GJ 1.5 1.4 1.3
Tier 0 Production Summary Tier 0 Type Curve Inputs
Sales Gas C5+ Total Sales Raw Gas EUR Bcf 8.2
mcf/d bbl/d boe/d Sales EUR Mboe 1,499
IP30 3,870 90 735 Capped Rate (Sales) MMcf/d 3.9
IP90 3,870 90 735 CGR (C5+) bbl/MMcf 23.3
IP180 3,748 87 712 DCCET Capital $MM $4.70
Birchcliff Energy Ltd.
May 2019